How Cash and Debit Card Users Are Subsidizing $30 Billion in Credit Card Rewards
A Harvard study reveals that people who pay with cash and debit cards effectively subsidize billions in points and perks for credit card users.
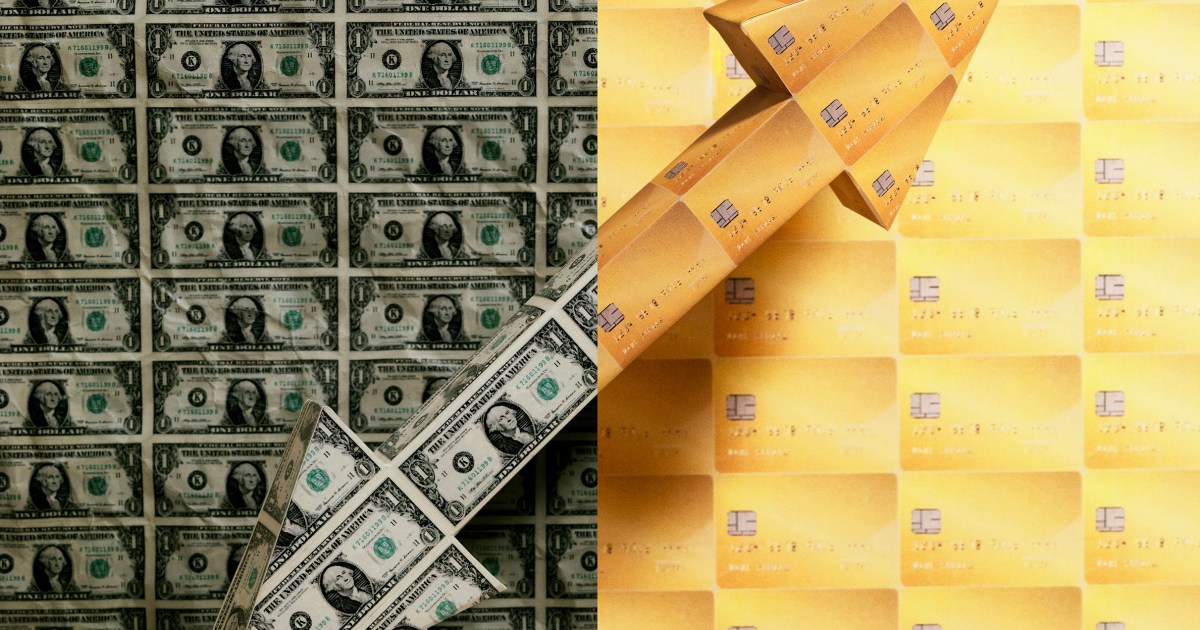
American consumers who pay with cash and debit cards are inadvertently subsidizing approximately $30 billion annually in rewards points and perks for credit card users, according to a new Harvard University study that exposes a significant wealth transfer hidden within the payment system. The research reveals how merchant fees and pricing structures create an economic burden that falls disproportionately on those who choose not to use credit cards.
The study analyzed the complex fee structures that merchants pay to process different types of payments, finding that credit card transactions typically cost retailers significantly more than cash or debit card payments. These higher processing fees, known as interchange fees, are built into the pricing of goods and services, meaning that all consumers pay higher prices regardless of their payment method. The credit card companies use a portion of these fees to fund rewards programs that benefit only their cardholders.
This system creates a regressive transfer of wealth, as consumers who use cash and debit cards tend to have lower incomes than those who use rewards credit cards. The Harvard researchers found that the subsidy flows from lower-income households, who are more likely to pay with cash or debit cards, to higher-income households that maximize credit card rewards. The effect is particularly pronounced in communities where credit card usage is less common due to economic circumstances or personal financial management preferences.
Merchants typically cannot offer different prices based on payment method due to contractual restrictions with credit card companies, though some businesses have begun implementing cash discounts or credit card surcharges where legally permitted. The study suggests that this inability to pass processing costs directly to credit card users perpetuates the hidden subsidy system. Small businesses are often hit particularly hard by these processing fees, which can represent a significant portion of their profit margins.
The findings have implications for consumer policy and financial regulation, as lawmakers and regulators consider whether current payment system structures are fair to all consumers. Some policy experts suggest that greater transparency in payment processing costs or changes to merchant pricing rules could help address the inequality. The study adds to growing scrutiny of credit card industry practices and their broader economic effects on different demographic groups.